Public Credit Registry: Meaning, Advantages, Challenges and Importance in India

Public Credit Registry is an important step taken to improve the credit system in India. In a growing economy like India, banks and financial institutions give loans to people, companies, farmers, and businesses. Before giving loans, lenders need proper information about borrowers. If the information is incomplete or incorrect, banks may give loans to risky borrowers, which can increase bad loans in the banking sector.
To solve this problem, the Reserve Bank of India (RBI) proposed the idea of a Public Credit Registry (PCR). A PCR is a central database that stores complete credit-related information about borrowers. It helps banks and financial institutions check the credit history of borrowers before approving loans.
The idea of Public Credit Registry became important after the increase in non-performing assets (NPAs) and loan defaults in India. The Y.M. Deosthalee Committee, formed by the RBI in 2018, recommended the establishment of PCR in India.
What is Public Credit Registry?
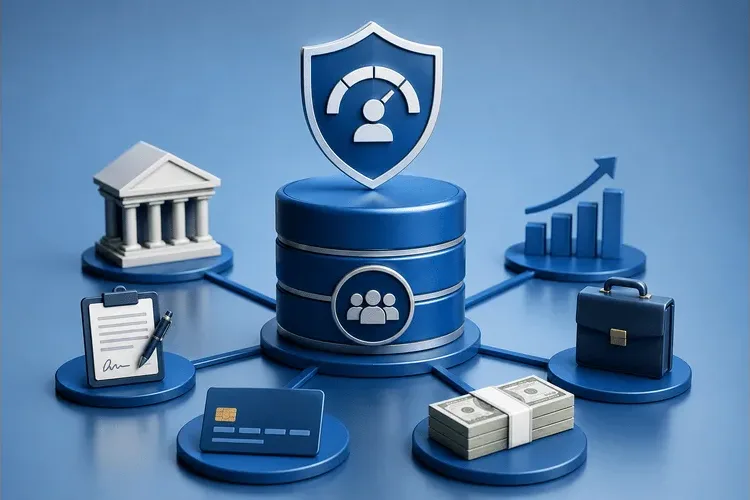
Public Credit Registry (PCR) is a large and centralized database that contains credit information of all borrowers. It stores complete details related to loans taken by individuals, companies, and institutions from different financial organizations.
The PCR will collect information from banks, non-banking financial companies (NBFCs), cooperative banks, corporate bond markets, and other lending institutions. All lenders will have to report loan details to this registry.
The Reserve Bank of India plans to establish the PCR as an independent unit under RBI supervision.
The main purpose of PCR is to provide complete, accurate, and updated information about borrowers to lending institutions.
Main Features of Public Credit Registry
1. Centralized Database
PCR will act as a single database for all loan-related information in India. All lenders will report borrower information to one platform.
2. Mandatory Reporting
Every financial institution will have to provide loan details to PCR. Reporting will be compulsory regardless of loan amount or borrower type.
3. Covers Different Types of Borrowings
PCR will include information about:
- Bank loans
- NBFC loans
- Corporate bonds
- External Commercial Borrowings (ECBs)
- Foreign Currency Convertible Bonds (FCCBs)
- Masala bonds
- Inter-corporate borrowings
4. Verified Information
The data stored in PCR will be verified by reporting institutions, reducing chances of fake or incorrect information.
5. Complete Loan Lifecycle
PCR will record all stages of a loan, from loan approval to repayment or default.
Why Does India Need Public Credit Registry?
India’s current credit information system has many weaknesses. Different institutions maintain separate databases, which creates confusion and incomplete information.
The following reasons explain why India needs PCR.
Shortcomings of the Current Credit Information System
1. Lack of Comprehensive Data
India’s current credit system is fragmented. RBI maintains records of borrowers with loans above a certain amount, while private credit agencies maintain separate databases.
Because of this, lenders may not get complete information about borrowers.
For example, a borrower who has defaulted on a loan from one institution may still receive another loan from a different institution due to missing data.
2. Dependence on Self-Disclosed Information
Banks often depend on information provided directly by borrowers such as:
- Income details
- KYC documents
- Assets and liabilities
- Contact details
- Net worth
Sometimes borrowers may provide incorrect or incomplete information.
3. Problem of Accuracy
Since data comes from many different sources, errors may occur during verification. Inaccurate records can affect both borrowers and lenders.
4. Delay in Updating Information
Many credit systems do not update information regularly. Because of delays, lenders may not get the latest financial status of borrowers.
5. Paid Credit Information Services
Private credit information companies charge lenders for accessing borrower data. This increases the cost for banks and financial institutions.
6. Limited Credit Access for Small Businesses
Small and Medium Enterprises (SMEs) often do not get loans because they lack proper credit history. Banks consider them risky borrowers.
This reduces credit flow to important sectors of the economy.
Advantages of Public Credit Registry
Public Credit Registry can improve the Indian financial system in many ways.
1. Reduction in Bad Loans
PCR will help lenders verify the complete credit history of borrowers. Banks can avoid giving loans to people or companies with poor repayment records.
This can reduce bad loans and Non-Performing Assets (NPAs).
2. Better Financial Inclusion
Many people in rural and underserved areas do not have formal credit history. PCR can help create proper financial records for such borrowers.
As a result, more people may get access to formal loans and banking services.
3. Support for MSMEs
Micro, Small and Medium Enterprises (MSMEs) are important for employment and economic growth. PCR can improve their access to credit by providing reliable financial data.
This may help small businesses grow faster.
4. Improved Regulation
PCR will help regulators like RBI monitor the health of the banking sector more effectively.
It can help identify:
- Financial risks
- Rising loan defaults
- Credit trends
- Sector-wise borrowing patterns
5. Better Quality of Information
A centralized system will improve the quality and reliability of borrower data.
Banks can make better lending decisions using accurate information.
6. Easier Loan Processing
Since all information will be available at one place, loan approval processes may become faster and simpler.
This can improve customer experience.
7. Removal of Information Asymmetry
Information asymmetry happens when borrowers know more about their financial condition than lenders.
PCR reduces this problem by giving lenders complete borrower information.
As a result, honest borrowers may receive loans at better interest rates.
8. Improvement in Ease of Doing Business
Easy access to credit is an important factor in improving business conditions.
PCR can improve India’s ranking in the ease of doing business by simplifying access to loans.
Challenges in Implementing Public Credit Registry
Although PCR has many benefits, there are several challenges in its implementation.
1. Need for Strong Legal Framework
PCR requires compulsory reporting by all financial institutions. This needs proper laws and regulations.
Creating such a legal framework can take time.
2. Privacy and Confidentiality Concerns
PCR will store sensitive financial information of millions of people and businesses.
Protecting this data from misuse, hacking, or leakage will be a major challenge.
3. Standardization of Data
Different banks and institutions use different systems and formats.
Creating one common reporting format for all institutions will be difficult.
4. Huge Amount of Data
PCR will store information about all loans, including small loans.
Managing such a massive amount of data efficiently will require strong technological infrastructure.
5. Technical Compatibility Issues
Banks use different software and digital platforms. Making all systems compatible with PCR may be technically challenging.
6. Cost of Implementation
Developing and maintaining a nationwide credit registry will require large investment in technology and cybersecurity.
Role of RBI in Public Credit Registry
The Reserve Bank of India plays a major role in establishing PCR.
The RBI is responsible for:
- Designing the PCR framework
- Supervising data collection
- Ensuring data security
- Regulating reporting institutions
- Monitoring compliance
The RBI aims to make PCR a reliable and transparent system for the entire financial sector.
Public Credit Registry and Economic Growth
A strong credit system is necessary for economic development. PCR can help the Indian economy in many ways.
Increased Lending
Banks will feel more confident while giving loans due to availability of verified borrower information.
Improved Investment
Businesses with good credit history may get easier access to funds for expansion.
Stronger Banking Sector
Reduction in bad loans can strengthen banks and improve financial stability.
Growth of Small Businesses
Better access to finance can help MSMEs create jobs and increase production.
Way Forward for Public Credit Registry
To make PCR successful, India needs a proper implementation strategy.
1. Phased Implementation
PCR should be introduced step-by-step to avoid disruption in the financial system.
2. Strong Data Protection Measures
Advanced cybersecurity systems must be used to protect sensitive information.
3. Coordination Among Stakeholders
Banks, NBFCs, regulators, and financial institutions should work together for smooth functioning.
4. Dedicated Supervisory Authority
A strong authority should monitor PCR operations and take action against rule violations.
5. Integration with Other Systems
PCR should be connected with other financial information systems like wilful defaulters’ lists and banking databases.
6. Regular Updating of Data
Institutions must update borrower information regularly to maintain accuracy.
Conclusion
Public Credit Registry is an important reform for strengthening India’s financial and banking system. It can provide complete and accurate credit information to lenders, reduce bad loans, improve financial inclusion, and increase transparency in lending.
Although there are challenges related to privacy, technology, and legal requirements, proper planning and strong regulation can help overcome them.
PCR has the potential to improve credit access for individuals and businesses, especially MSMEs and underserved sectors. It can also strengthen the banking sector and support long-term economic growth in India.
With proper implementation, Public Credit Registry can become a major tool for building a more transparent, efficient, and trustworthy credit system in the country.
FAQs on Public Credit Registry
1. What is Public Credit Registry (PCR)?
Public Credit Registry is a centralized database that stores complete credit information of borrowers in India.
2. Who proposed the Public Credit Registry in India?
The Y.M. Deosthalee Committee set up by the Reserve Bank of India (RBI) recommended the creation of PCR in 2018.
3. What is the main purpose of PCR?
The main purpose of PCR is to provide accurate and complete borrower information to banks and financial institutions.
4. How does PCR help banks?
PCR helps banks verify borrower credit history and reduce the risk of bad loans and defaults.
5. What types of loans are included in PCR?
PCR includes bank loans, NBFC loans, corporate bonds, ECBs, FCCBs, and other borrowings.
6. How does PCR support MSMEs?
PCR improves access to credit for MSMEs by providing verified financial information and credit history.
7. What are the major challenges of PCR?
Privacy concerns, huge data management, technical compatibility, and legal framework are major challenges.
8. Which institution will manage PCR in India?
The Reserve Bank of India (RBI) is expected to supervise and manage the PCR system.